Market overview of the Rewetting Drops Market
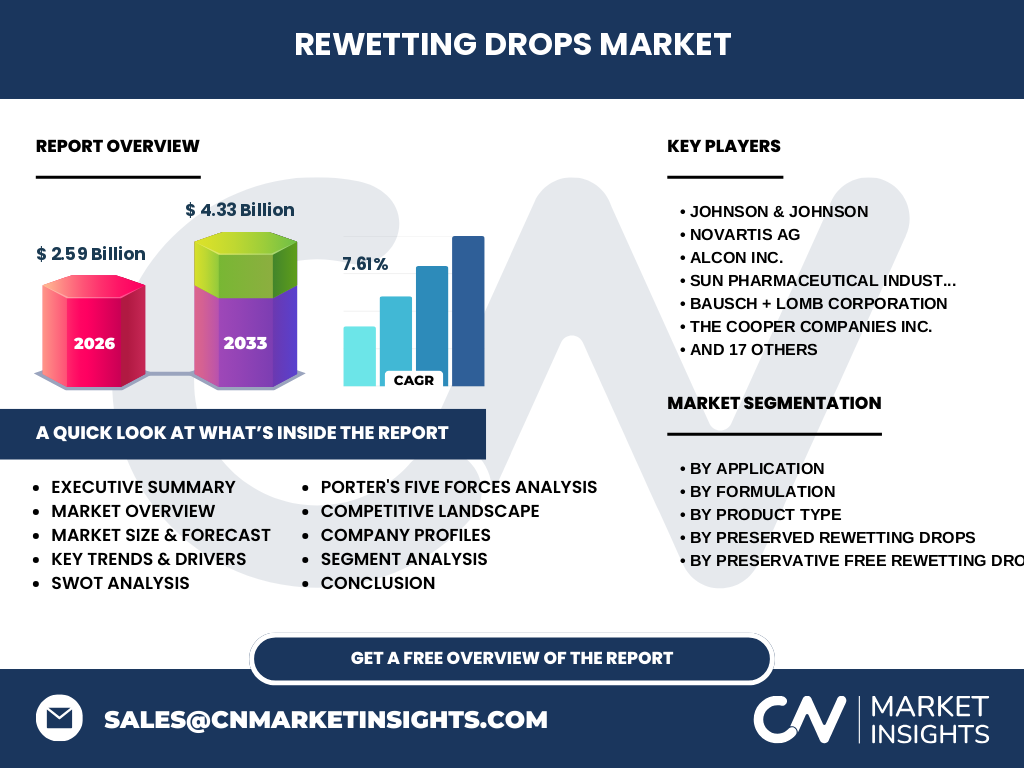
Our analysis indicates that the Rewetting Drops Market encompasses specialized ocular formulations designed to restore the tear film lipid layer and alleviate dryness. Valued at 2.59 Billion in 2026, the industry is critical for addressing global increases in digital eye strain and chronic ocular surface disorders.
What are the structural growth drivers and challenges shaping industry dynamics?
The market is propelled by rising screen time and an aging demographic prone to meibomian gland dysfunction. Conversely, stringent FDA and EMA regulatory filings for preservative systems present entry barriers. Industry players must navigate complex raw material supply chains for hyaluronic acid and carboxymethylcellulose.
Emerging trends and growth patterns in ocular therapeutics
The shift toward preservative-free formulations is accelerating rapidly. Consumers increasingly favor single-dose vials and advanced multi-dose preservative-free bottles to mitigate ocular surface toxicity caused by traditional agents like benzalkonium chloride, transforming the competitive landscape for major manufacturers.
COVID-19 impact analysis and pandemic recovery trajectory
Pandemic-induced remote work environments drastically amplified digital screen consumption, permanently altering consumer behavior toward daily eye care. Supply chain bottlenecks for active pharmaceutical ingredients initially challenged manufacturers, but accelerated e-commerce adoption ultimately stabilized distribution channels across global markets.
Competitive benchmarking and strategic market concentration
The industry features intense competition among pharmaceutical giants. Companies like Alcon Inc., Novartis AG, and Bausch + Lomb Corporation leverage extensive distribution networks, while specialized firms such as Laboratoires Théa SAS capture market share through innovative preservative-free delivery systems.
Executive summary of key findings
Our research projects the Rewetting Drops Market market size to expand from 2.59 Billion in 2026 to 4.33 Billion by 2033. Achieving a robust CAGR of 7.61%, the sector offers high-margin opportunities for firms investing in advanced gel and emulsion drop formulations.
Long-term market forecast from 2027 to 2033
Driven by persistent demand for contact lens moisturization and allergy relief, the forecast period anticipates sustained compounding growth. The trajectory from 2027 to 2033 reflects heightened consumer health expenditure and broader accessibility of over-the-counter ophthalmic products across emerging economies.
Segmentation analysis across applications and formulations
Segmentation is categorized by application into dry eye syndrome, contact lens moisturization, and allergies. Formulations span liquid drops, gel drops, and emulsion drops, while product types divide into preservative-free and preserved variants utilizing advanced buffering systems like Purite and Sofzia.
Geographic distribution and regional performance
North America and Europe maintain dominant market shares due to high healthcare awareness and advanced diagnostic infrastructure for dry eye disease. Meanwhile, Asia-Pacific represents the fastest-growing regional market, propelled by rapid urbanization, rising disposable incomes, and widespread digital device penetration.
In-depth regional review of high-growth territories
In North America, stringent regulatory frameworks enforced by the FDA dictate strict compliance for sterile manufacturing facilities. Conversely, the Asia-Pacific region exhibits accelerating demand for affordable over-the-counter soothing drops, encouraging localized manufacturing partnerships in key hubs like India and Japan.
Company profiles and strategic positioning
Industry leaders maintain distinct strategic advantages. Johnson & Johnson and The Cooper Companies Inc. dominate contact lens-adjacent drop categories, whereas Rohto Pharmaceutical Co. Ltd. and Santen Pharmaceutical Co. Ltd. capitalize on robust regional footprints in Asia's OTC ophthalmic retail sectors.
Porter's Five Forces analysis of the ocular surface sector
Bargaining power of suppliers remains moderate due to specialized excipients, while buyer power is high given intense retail competition. Threat of substitutes is low, but high capital requirements for sterile fill-finish facilities effectively moderate the threat of new market entrants.
SWOT analysis of the global eye drop industry
Key strengths lie in strong brand loyalty and advanced polymer delivery technologies. Weaknesses involve high R&D costs for sterile packaging. Opportunities abound in emerging markets, though regulatory compliance shifts represent ongoing threats to established product portfolios.
Value chain analysis from raw materials to end-users
The value chain originates with chemical synthesis of active ingredients and polymers, progressing through sterile compounding and aseptic blow-fill-seal packaging. Logistics hubs and major port facilities ensure cold-chain integrity before products reach retail pharmacies, clinics, and direct-to-consumer e-commerce channels.
Investment insights and strategic recommendations
Investors should prioritize companies developing proprietary multi-dose preservative-free bottle technology. High-potential areas include targeted formulations for computer vision syndrome and strategic acquisitions of regional players holding established regulatory approvals in high-growth developing economies.
Conclusion and core industry takeaways
The Rewetting Drops Market industry trends underscore a decisive pivot toward patient safety and comfort. With a projected valuation of 4.33 Billion by 2033, innovation in preservative-free delivery remains the ultimate catalyst for long-term commercial success.
Research methodology and data triangulation protocols
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary qualitative interviews with ophthalmology key opinion leaders, and secondary macroeconomic indicators. This multi-layered approach ensures precise sizing of the Rewetting Drops Market market size.
Scope of the report and analytical limitations
This report covers global manufacturing, distribution, and consumption dynamics across specified formulations and applications. Limitations include potential fluctuations in regional healthcare reimbursement policies and unpredictable macroeconomic inflationary pressures affecting raw material procurement costs.
Recent developments, strategic moves, and product launches
Recent strategic activity highlights aggressive capital expenditure toward eco-friendly, multi-dose preservative-free packaging lines. Key market participants such as Bausch + Lomb Corporation and Alcon Inc. have actively pursued distribution agreements and portfolio expansions to capture rising dry eye therapeutic demand.